People moved $1.2 billion through stablecoin debit cards in September 2026 alone. That is roughly three times what they spent a year earlier, and Stripe stablecoin cards are a big part of that jump. The company wants its cards working in more than 100 countries by the end of this year. For freelancers, gig workers, and small business owners who get paid in digital dollars, that detail is not a footnote. It is the difference between money that sits locked in an app and money you can actually hand over at the corner store.
How a Stripe Stablecoin Card Works at the Checkout
Picture Grace, a freelance virtual assistant in Cebu, the Philippines. Clients in the United States and Australia pay her in USDC, a stablecoin pegged to the dollar. Right now, spending that money means moving it to a local exchange, converting it to pesos, and waiting for a bank transfer to clear. That detour can cost her a slice of every payment, plus a day or two of waiting before she can buy groceries.
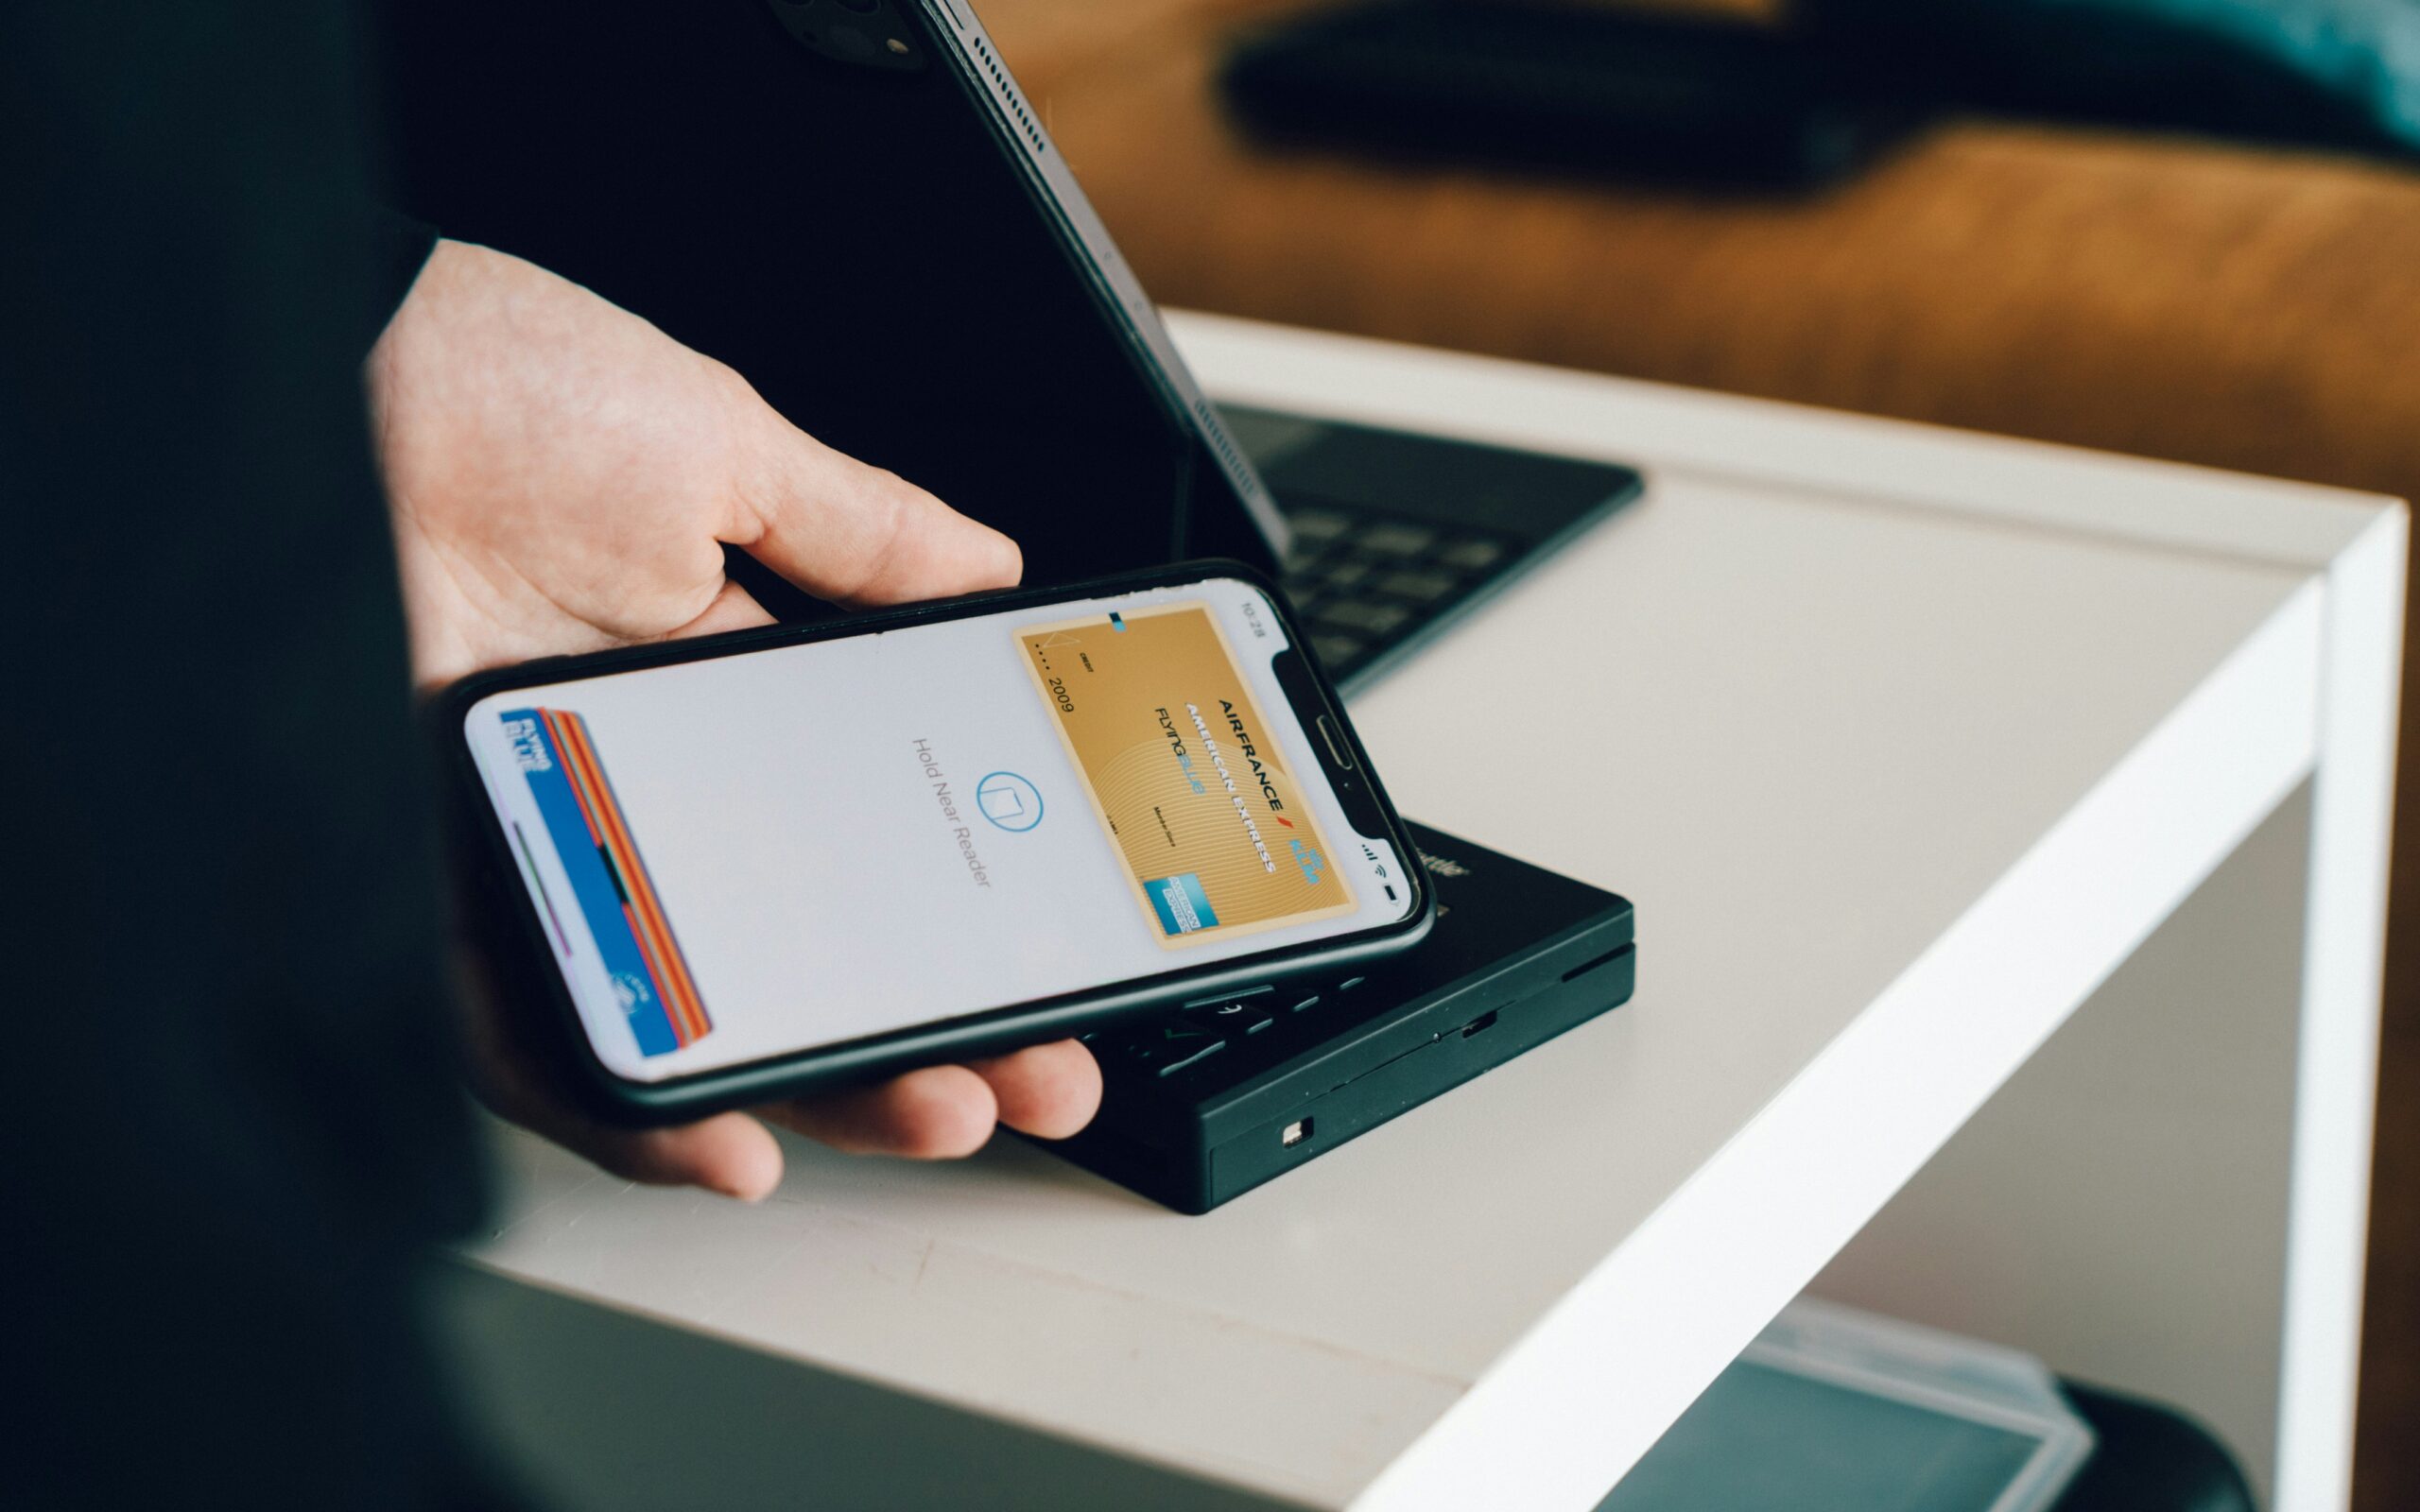
A Stripe stablecoin card skips that whole detour. It runs on Bridge, the stablecoin company Stripe bought for $1.1 billion, and it rides on Visa’s existing card network. You hold stablecoins behind the scenes. You tap, swipe, or insert the card at checkout like any other debit card. The conversion happens instantly, right at the register. The cashier never has to know your dollars started out as crypto.
The Real Savings in Fees and Days
Converting stablecoins into local cash through small exchanges is rarely free. Spreads and fees in many emerging markets commonly eat somewhere between 3 and 6 percent of each transfer. The bank transfer afterward can take one to three days to clear. On a $500 payment, a 5 percent spread quietly removes $25 before you spend a cent of it.
A card that spends stablecoins directly closes most of that gap:
- No separate cash-out step before you’re allowed to spend
- Conversion happens at the register, not days earlier at a middleman’s rate
- Access to Visa’s network of more than 175 million merchant locations worldwide
- One card to track, instead of juggling a crypto wallet and a separate bank app
Visa’s head of crypto, Cuy Sheffield, has summed up the company’s reasoning simply:
“Visa is committed to meeting businesses where they operate, and increasingly that is onchain.”
Visa isn’t alone in seeing the volume grow. The company reports more than 160 stablecoin-linked card programs now live worldwide, with payment volume up nearly 200 percent year over year, a figure also covered by Coin Alert News this week.
Where This Is Headed Next
Stripe launched its card with Visa in March 2026, live in 18 countries, mostly across Latin America. The Block reported that Africa, Asia-Pacific, Europe, and the Middle East come next, with the 100-plus country target set for the end of 2026.
That expansion would join other recent moves putting stablecoins into ordinary people’s hands. Kora’s new payment rail already cuts African wire waits from fourteen days to minutes. Binance Pay recently turned ten million ordinary shops in Japan into crypto-friendly checkouts. None of this guarantees a smooth rollout everywhere. Local rules, card issuers, and bank partnerships will decide who gets a card first. Stripe’s own timeline calls the 100-country goal a plan, not a finished rollout.
Still, the direction is clear. If you already get paid in stablecoins, or know someone who does, the question worth asking isn’t whether a card like this eventually reaches you. It’s whether your wallet app or bank will tell you when it does. Check the settings menu now, so you’re not the last to know.