What if the money you earned Friday night showed up in an app you already use, before Monday morning instead of after it?
MassPay, a US payouts company, said on October 8, 2026 that platforms using its service can now send Cash App payouts straight into a recipient’s balance. The company’s own announcement says delivery lands “in near real time” once a client turns the option on. Payments Dive and The Paypers both covered the move this week, and MassPay’s data runs the transfer over stablecoin rails behind the scenes. The recipient never has to open a crypto app or touch a token to use it.
How MassPay’s Cash App payouts actually work
MassPay already pays out through banks, cards, and mobile wallets in roughly 180 countries. Cash App is a new option layered onto that same system, and it only works for US clients right now. Here’s the path a payment takes, based on MassPay’s own description:
- A business, like a gig platform, marketplace, or gaming operator, tells MassPay a job or sale is complete.
- MassPay converts the client’s funds into a stablecoin, a digital dollar built to hold its value, and moves it over blockchain rails instead of the banking system.
- MassPay converts that stablecoin back into ordinary dollars and deposits it into the recipient’s Cash App balance.
- The recipient spends, saves, or transfers the money from Cash App like any other deposit, with no new app, login, or bank account required.
MassPay says the service charges a fee, though it hasn’t published the amount, and that it doesn’t charge anything on a payment that fails to land. Existing clients need to ask their account team to switch Cash App on, so it isn’t automatic for every gig worker overnight.
Who this is actually built for
MassPay names a specific group of earners in its announcement:
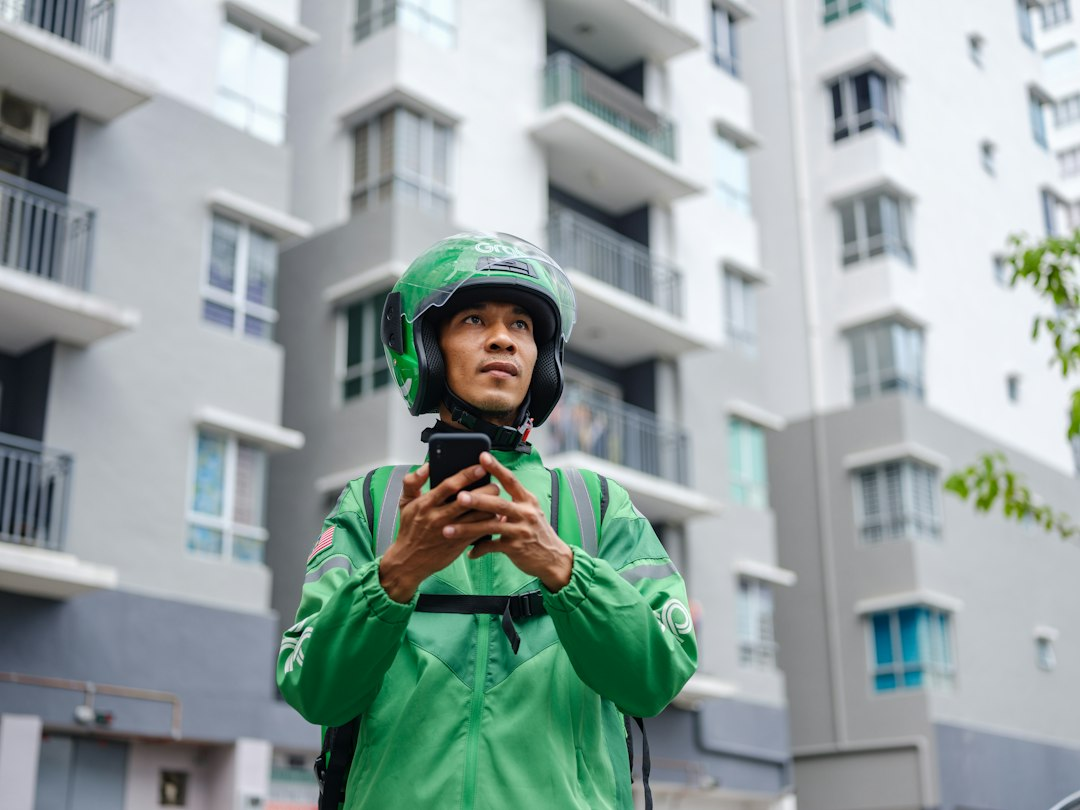
- Gig and marketplace workers, like rideshare drivers, delivery couriers, and online sellers, who get paid once a trip or sale is done.
- Creators and affiliates whose income depends on platforms settling up regularly.
- Freelancers and contractors who’ve historically waited on a bank transfer to clear.
- People who win money through gaming or sports betting apps, or who receive insurance claim payouts.
Picture an illustrative example: a single dad we’ll call Marcus drives for a delivery app on weekends to cover his daughter’s soccer fees. He already banks almost entirely through Cash App. Before this, a platform payout might land in a traditional bank account he rarely checks, then take a day or two to become spendable money. Now, if his platform turns the feature on, that same payout can show up where he actually looks for it.
“The best payout experience is the one the recipient never has to think about,” MassPay CEO Ran Grushkowsky said in the announcement.
That line gets at something real. Most people don’t want a lesson in blockchain rails. They want their money, on time, in the app where they already keep it.
The stablecoin part you’ll never see
This launch fits a pattern Payments Dive reported on October 13, 2026: stablecoin infrastructure is increasingly hidden inside products people already use, rather than sold to them directly. The same article notes that Western Union and MoneyGram are both MassPay clients, and that Rain, a separate stablecoin company, launched its own consumer wallet the same week. MassPay’s chief executive told the outlet that stablecoins now carry roughly 10% of the tens of billions of dollars MassPay processes annually, with about half of its total volume crossing borders.
That’s worth pausing on, because it cuts against how most stablecoin stories get told. Coverage of apps like Samsung Wallet or crypto-linked debit cards usually involves a person holding a stablecoin directly, which means they carry the risk if that coin ever slips below a dollar. Here, the stablecoin is plumbing. Cash App users just see dollars, the same as a direct deposit from an employer. The tradeoff is that MassPay and Cash App, not the saver, decide where and how the money moves behind the scenes, and none of that is yet detailed publicly.
Why It Matters to You
If you drive, deliver, freelance, sell on a marketplace, or get paid through a platform that uses MassPay, this could mean your earnings land in an app you already check, without opening a new account. It could also mean you see that money sooner than a traditional bank transfer, since MassPay describes delivery as near real time rather than one to three business days. None of this is guaranteed yet: it depends on your specific platform choosing to switch Cash App on, and it only applies if you’re in the United States.
What we don’t know yet
- MassPay hasn’t published what the payout fee actually costs, so there’s no way yet to compare it against a standard bank transfer or Cash App’s existing instant-deposit option.
- “Near real time” isn’t the same as instant, and MassPay gives no minimum or average delivery time.
- The feature is US-only. MassPay’s broader network covers 180 countries, but Cash App payouts don’t, at least for now.
- No platform has to turn this on. Existing MassPay clients must request it, so most gig workers won’t see it in their app this week even if their platform uses MassPay.
- MassPay hasn’t released how many payments have moved through the Cash App option, so there’s no way to gauge early adoption.
Watch whether MassPay or a named platform discloses a fee schedule, and whether other payout companies follow with their own Cash App or Venmo-style integrations. That’s the detail that will decide whether this actually beats what gig workers already have.
Sources
- MassPay: Get Paid Where You Already Live: Cash App Payouts Are Now on MassPay (Oct 8, 2026)
- The Paypers: MassPay adds Cash App as payout option for US clients (Oct 12, 2026)
- Payments Dive: Stablecoin startups advance payments (Oct 13, 2026)