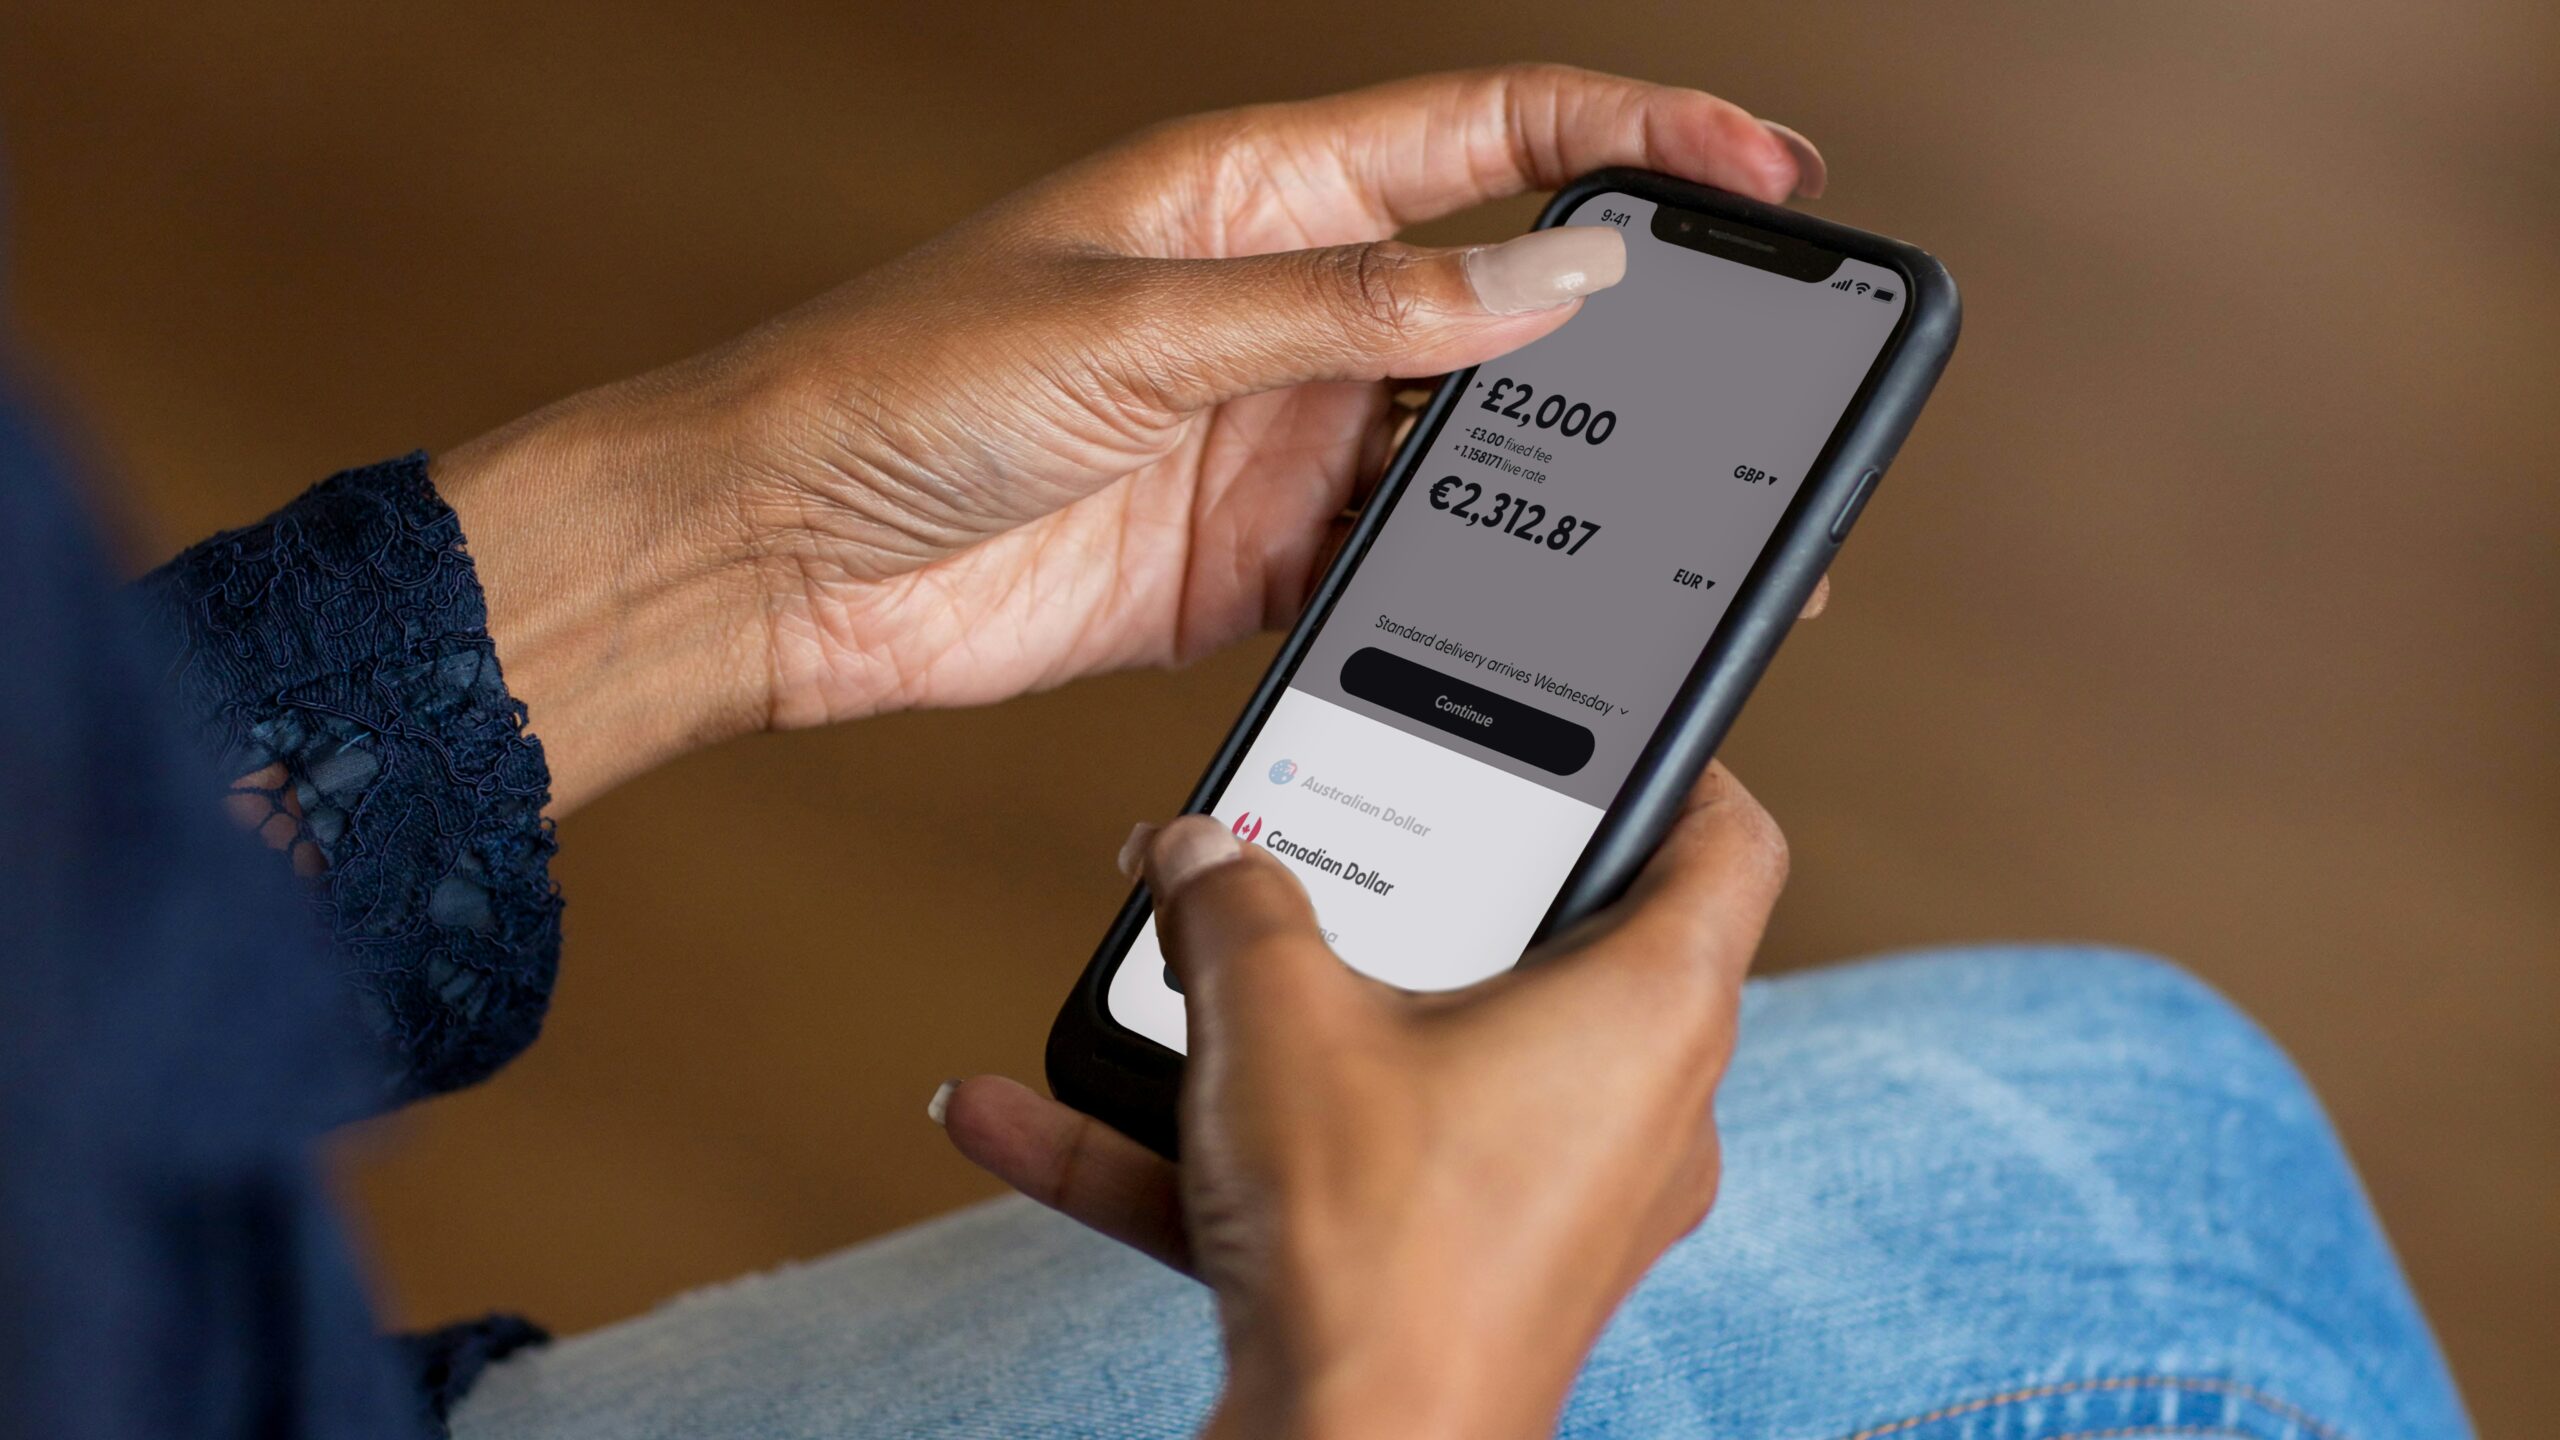
Picture a small business owner in Buenos Aires who gets paid in pesos and watches the value slip before the invoice even clears. On September 10, Nubank gave her a new option: the Nu Global stablecoin account, which turns ordinary deposits into Circle’s dollar-pegged USDC inside the same banking app she already opens every day.
Nubank runs the accounts for more than 140 million customers across Brazil, Mexico, and Colombia, and it just extended that reach into digital dollars and euros. Move money into Nu Global, and it becomes a stable, dollar- or euro-denominated balance that doesn’t lose ground when the local currency wobbles. No crypto exchange, no separate wallet app, no seed phrase to memorize.
How the Nu Global Stablecoin Account Works for Everyday Savers
Customers who open a Nu Global stablecoin account earn 3.50% APY on dollar balances and 2.20% APY on euro balances, calculated and paid daily rather than locked up for months. Transfers move free of charge across more than 35 countries in Europe and Latin America, including Argentina, Chile, Peru, and Uruguay, with no foreign-exchange markup buried in the rate. A freelance designer in Lima who bills a client in Madrid can collect euros, convert them to dollars, and wire a portion home to relatives in Bolivia without three separate institutions each skimming a cut.
That routing used to cost real money. Sending funds through a currency exchange or a local money changer typically ate 3 to 5 percent per hop, sometimes more once a spread got tacked on. Cutting that from a $500 transfer puts $15 to $25 back in someone’s pocket every time they send it, and for a family that wires money home monthly, the savings compound fast.
A Card That Spends the Balance Without a Crypto Detour
Nu Global ships with a virtual Mastercard, so dollars sitting in the account pay for groceries in São Paulo or a hotel in Lisbon the same way a normal debit card would. That’s the same problem Marqeta and BVNK are solving with their own stablecoin-backed debit cards, but Nubank skips the middleman. The bank its customers already trust built the spending rail in-house, so nobody bounces between a crypto app and a banking app just to buy lunch.
Why Nubank’s US Launch Matters Too
Nubank used the same announcement to open Nu US, an FDIC-insured account issued with Lead Bank. It pays 3.50% APY, boostable to 4.50% on balances up to $10,000, and pairs with a no-annual-fee Mastercard offering 1.5% cashback. “The combination of our customer centricity and fully mobile banking model allows us to pass efficiencies to customers,” said Cristina Junqueira, Nu US’s CEO. David Vélez, Nubank’s CEO, called the broader push the start of a “multi-decade journey” beyond Latin America.
The timing isn’t an accident. Nubank is betting that the yield-and-simplicity pitch that won over 140 million Latin American customers, an approach that echoes what Plenti already built with digital dollar accounts for the region’s freelancers, will also win over US customers tired of checking accounts that pay next to nothing.
None of this requires understanding blockchain or opening a crypto exchange account. Digital dollars just got folded into a banking app tens of millions of people already open every morning. For the business owner in Buenos Aires, one tap now turns shrinking pesos into a balance that holds its value, plus a card that spends it without a detour through a currency desk.