A new peaq robot financing model just went live, and it turns a machine’s own work record into loan collateral. Here’s what that could mean for shops like Renata’s.
Renata runs a six-person metal shop outside Milwaukee. She has priced out a collaborative robot for two years straight. The machine costs about $45,000, and her bank wants 20 percent down plus three years of clean books she doesn’t have, since half her revenue rides on one seasonal contract. So she keeps bending sheet metal by hand.
What Doosan and peaq Actually Did
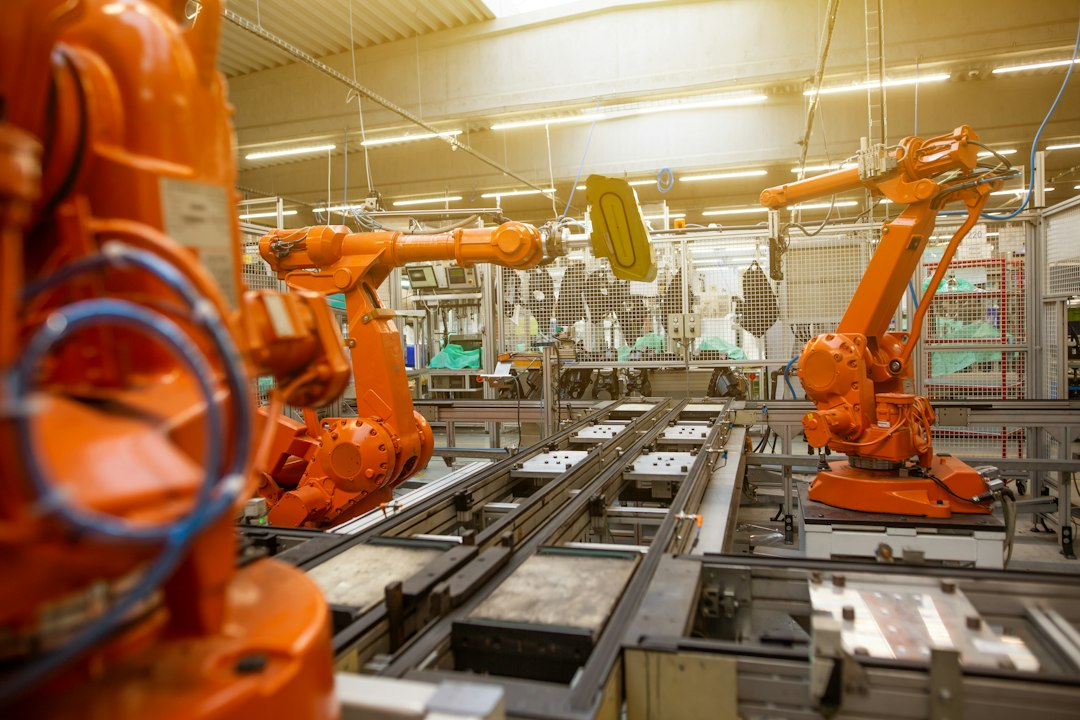
On September 17, Doosan Robotics, one of the world’s five largest cobot makers, put its first unit on peaqOS Pro, a system built on the Solana blockchain. That unit, an A0509 model, now carries its own digital identity, its own wallet, and a permanent, verifiable performance record, viewable at machines.peaq.xyz. Doosan operates in 45 countries, so this isn’t a lab experiment. (Solana Compass)
One safeguard matters here. The robot shares only attestations and aggregate numbers, never camera footage or raw sensor data, so Doosan keeps its trade secrets while still proving the machine works.
Why a Robot Needs a Credit Score
This is the part that matters for Renata. Every activated machine builds a Machine Credit Rating from its documented uptime and output. A lender can eventually finance the robot itself against that rating, the way a mortgage lender assesses a house instead of just the buyer’s paycheck.
“Our customers buy a robot for their busiest hour and pay for all the others. A robot at the cutting edge should be able to account for itself and earn in the hours nobody planned for, without handing over a single frame of what it saw.” (Michael Ryu, Head of Europe, Doosan Robotics)
peaq’s Chief Business Officer, Martin El-Khouri, said it more plainly: lenders already in peaq’s network have asked about backing machines this way.
What peaq’s Robot Financing Model Saves You
For a small shop owner, this could mean real money and real time:
- Financing access: a documented performance record becomes usable collateral, which could lower the down payment or interest rate a small operator needs to qualify.
- Idle-hour income: many cobots in low-volume shops sit unused a third of a shift or more. Renting out that idle time, verified on-chain, turns dead capacity into cash that pays down the loan faster.
- Fewer disputes: a public, tamper-resistant uptime record cuts the back-and-forth between lenders, insurers, and owners over whether a machine performed.
Picture a bakery outside Atlanta leasing a delivery robot on weekdays. Under the old model, it just depreciates on Saturday. Under this one, it gets rented to a neighboring warehouse and earns its keep.
Part of a Bigger Shift
This fits a broader push to turn hard-to-finance assets into things a normal lender can price. It’s the same logic behind efforts to tokenize catastrophe bonds and drop their buy-in to $5,000. A peaqOS-equipped robot has already landed with students at the Technical University of Munich, with an October hackathon planned to test what developers build on it. (Solana Compass)
What to Watch Next
None of this helps Renata tomorrow. Machine-backed lending needs real banks willing to underwrite against on-chain data, and that takes months, not days. But picture a handful of lenders treating a Machine Credit Rating like a paid-off delivery van. The math changes fast for every small manufacturer on the fence about automation. Watch what comes out of October’s hackathon. Then ask your own equipment lender, this year, whether they’ve even heard of this yet.